CURATED INVESTMENT OPPORTUNITIES • GROUNDFLOOR
Invest on your terms with Groundfloor Notes. Choose from a variety of high-yield, fixed-rate Notes offering up to 9%, lock in your return from day one, and earn predictable income with no investor fees.
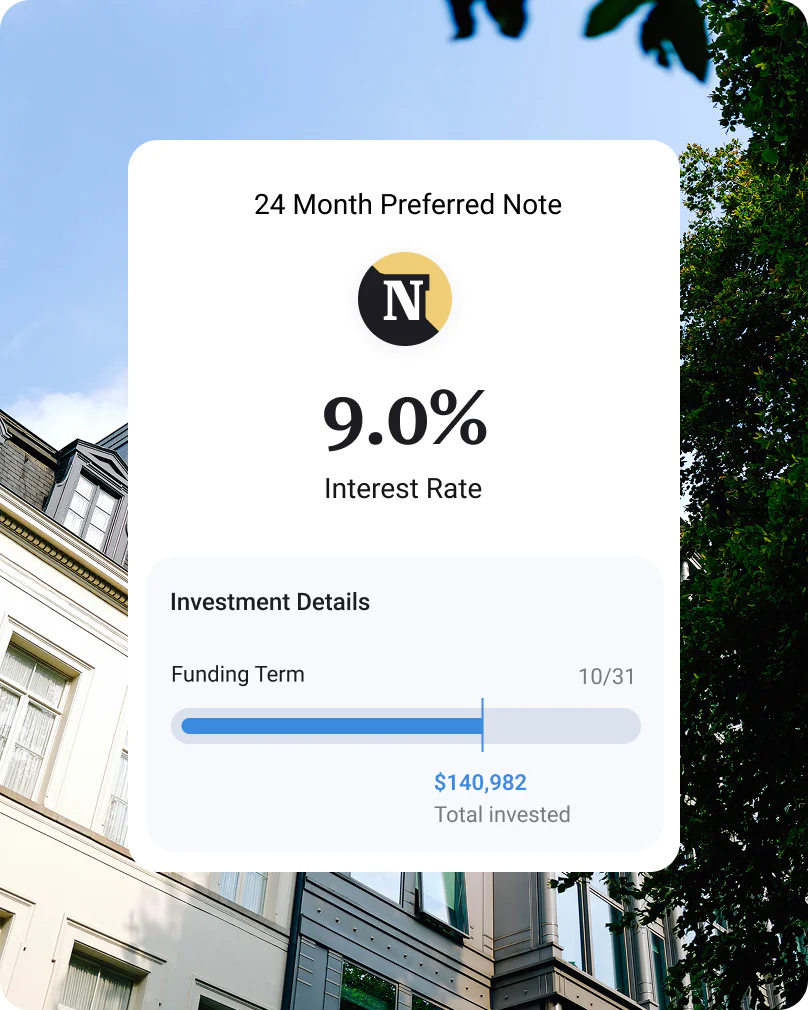
Choose the rate and term that fit your goals. Open to accredited and non-accredited investors.
Accredited Investors
7.0%
Fixed Rate
Our shortest accredited term – a premium rate with a quicker return.
8.5%
Fixed Rate
A balanced structure – an elevated fixed rate over a one-year commitment.
Our highest fixed return – lock in a premium rate and earn monthly income for two years.
Fixed Rate
OPEN TO ALL INVESTORS

8.0%
Fixed Rate
6.0%
Fixed Rate
5.0%
Fixed Rate
5.0%
Fixed Rate
6.0%
Fixed Rate
3-Month Note
8.0%
Fixed Rate
12-Month Signature Note
SEE FOR YOURSELF
5-9.0%
LOCK IT IN
The rate you see is locked in for the entirety of the term you choose. No fees.
Pick Your Term
Groundfloor has originated $2.2 billion in real estate loans to vetted residential builders since 2013. Notes give you direct exposure to that loan engine without picking properties, managing tenants, or competing for deals
Your chosen rate and term are locked in the moment you invest, no matter what the market does.
Short-term loans go to residential builders for renovations, rehabs, and new construction.
In any recovery, Groundfloor's first-lien claim is paid before junior debt or equity.
Depending on the Note you choose, you may be paid interest either monthly or at maturity.
Depending on the Note you choose, you may be paid interest either monthly or at maturity.
Structural Details
Every Note is backed by a first-lien position on every property.
When a residential builder takes a loan from Groundfloor, the loan is secured by a first-lien position on the property. In any recovery scenario such as a sale, refinancing, or foreclosure — the first lien holder is paid before any other claim.
That's the same structure a bank uses when it issues a mortgage. The difference: with a Groundfloor Note, you're the one earning the yield on the loan instead of the bank.
First-lien protection doesn't eliminate risk. It defines where you sit in line if something goes wrong. The position itself is the structural advantage.
First-lien holder
(you, via Groundfloor) PAID FIRST
Second-lien / mezzanine debt
PAID AFTER
Junior Debt
PAID AFTER
Equity (the builder)
PAID LAST
Capital stack in a typical residential real estate loan
First-lien holder (you, via Groundfloor) PAID FIRST
Second-lien / Mezzanine Debt PAID AFTER
Junior Debt PAID AFTER
Equity (the builder) PAID LAST
Capital stack in a typical residential real estate loan
100% Repayment Track Record
Every Note Groundfloor has issued since the program launched in 2018 has paid 100% of principal and interest. The track record lives in our SEC filings.
Through inflation, rate hikes, and a regional banking crisis — every Note has paid in full and on time.
Funded across 12 years of operating history
Individual investors on the platform
Principal & interest paid on every Note since 2018
HOW NOTES COMPARE
Short-duration fixed income products differ in structure as much as in yield. Here is how the 12-month Signature Note sits next to the alternatives investors typically consider.
$15,000 INVESTED · 12 MONTHS
JUly 2026 RATES
2026 RATES
$15,000 in a Groundfloor 12-Month Signature Note earns $1,375 in interest + starting bonus over 12 months at 8.0% fixed rate.
You’ll receive $106.25 in interest each month, plus the $100 starting bonus.
The same $15,000 in a 12-month bank CD at the FDIC national average of 1.55% earns $232.50, paid once at maturity.
That’s $1,142.50 more in total earnings over the same 12-month period.
+$1,142.50
More interest than a CD over 12 months
Signature Note vs. 12-month bank CD on a $15,000 investment
New investors: invest $1,000+ in Notes and get a $100 bonus on top of your interest with NOTES100 — on a $15,000 Signature Note, that lifts first-year earnings to $1,375.00.

1.55% APY · FDIC national average · Paid at maturity
$100 minimum for 1mo/3mo, $1,000 for the 12mo Signature. Reg A qualified.
Illustrative comparison. Assumes $15,000 invested at 8.0% fixed APR in the Groundfloor 12-Month Signature Note (monthly distributions of $106.25 × 12 = $1,275.00 total interest) versus a 12-month bank CD at the June 2026 FDIC national average yield of 1.55%. Notes are not bank deposits and are not FDIC-insured. Past performance does not guarantee future results. $100 new-investor bonus available for a limited time on first investments of $1,000+ in Notes, subject to promotional terms. Bonus is not interest and not included in the chart figures.
See for yourself
| ACCREDITED 24-MONTH PREFERRED NOTE |
NON-ACCREDITED GROUNDFLOOR SIGNATURE NOTE |
12-MONTH BANK CD (FDIC AVG) |
OPEN-ENDED RE INCOME REIT |
HIGH-YIELD SAVINGS |
|
|---|---|---|---|---|---|
| Stated yield | 9.0% fixed APR | 8.0% fixed APR | 1.55% APR | ~6-8% variable | ~3.5–4% variable |
| Rate locked? | Yes — locked at investment | Yes — locked at investment | Yes — locked at investment | No — adjusts monthly | No — bank can change |
| Term | 24 months, defined | 12 months, defined | 12 months, defined | Perpetual / open-ended | None |
| Distributions | Monthly | Monthly | At maturity | Monthly | Monthly accrual |
| Collateral / backing | First-lien on real estate | First-lien on real estate | FDIC to $250K | Equity claim on portfolio | FDIC to $250K |
| Investor fees | Zero | Zero | None | ~1% AUM annually | None |
| Minimum | $100,000 | $1,000 | $100+ | ~$100 | $0–$1,000 |
| Accreditation | Yes — accredited investors only | No — open to all | No | No — open to all | No |
| Track record | 100% paid since 2018 | 100% paid since 2018 | FDIC backing | ~4 years operating | FDIC backing |
LOCK IT IN
The rate you see is locked in for the entirety of the term you choose. No fees.
WHO NOTES ARE FOR
Notes are flexible, high-yield investments designed for any investor.
The Signature Note delivers fixed 8.0% for the same 12-month commitment — first-lien backing instead of FDIC backing. Different protection, materially different yield.
Notes give you a fixed alternative with monthly flexibility — high yields without giving up control of your cash for long lockups.
QUESTIONS
Notes are designed to be understood. If your question isn’t here, our Investor Success team is available at [email protected] — we don’t outsource to a chatbot.
A Note is a fixed-rate, fixed-term debt security — predictable income for a defined period.
We also offer an actively managed REIT with a 3-year vintage targeting a 9–10% IRR, individual LROs, and curated limited availability private market offerings for accredited investors. Many investors hold multiple.
LOCK IT IN
Skip the market swings.
Groundfloor Notes are offered under Regulation A of the Securities Act of 1933. Notes are not bank deposits, are not insured by the FDIC, and involve risk of loss. Past performance is not indicative of future results. All rates current as of May 2026 and may be adjusted monthly for new Notes. Read the offering circular before investing. © 2026 Groundfloor Finance Inc.”