12 months$10M Note limit
10.5%fixed, annualized
Matures November 30, 2027
Illustrative earnings on $100,000$10,500 at maturity
LIMITED-TIME HOLIDAY NOTES · NOV 16–30
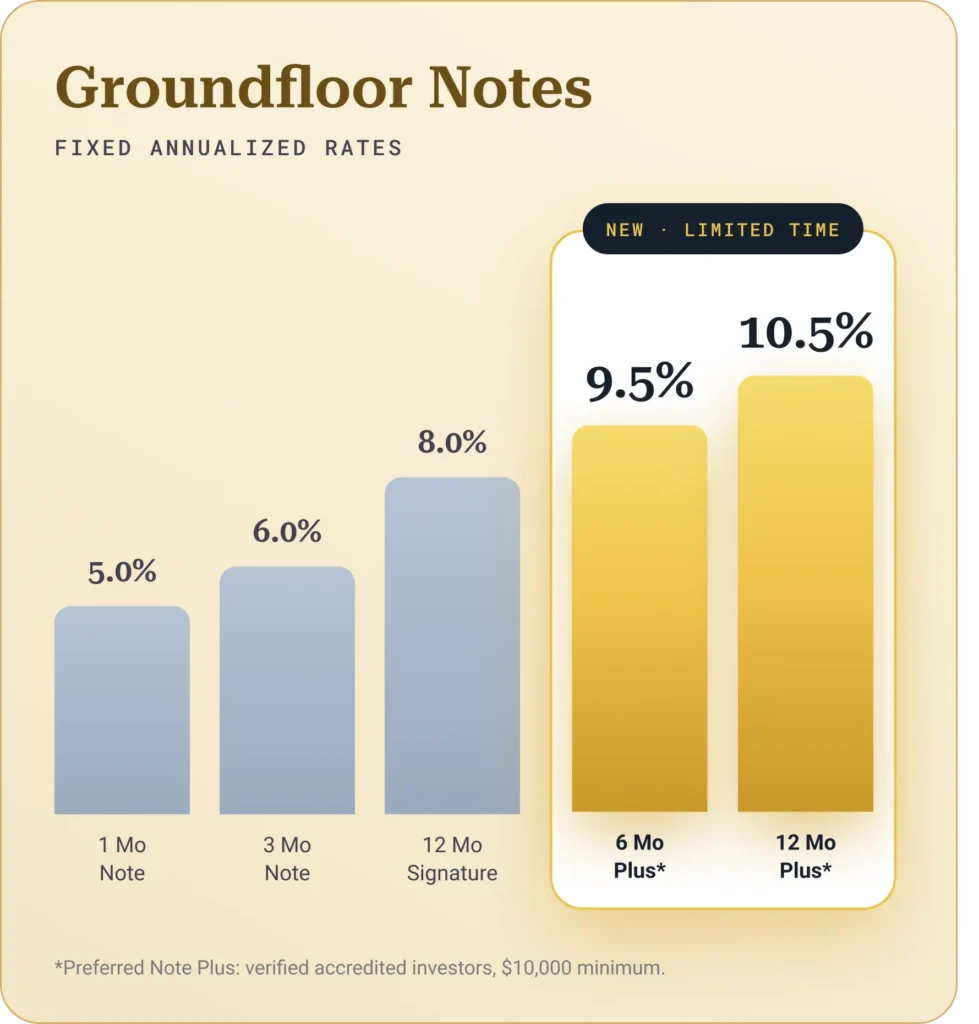
Preferred Note Plus pays verified accredited investors a fixed 10.5% for 12 months, or 9.5% for 6. It’s open through November 30.
Not accredited? You can still earn 8.0% fixed for 12 months with the Signature Note, plus $150 bonus on your first investment. Either way, you know the rate, the amount and the maturity date before you invest a dollar.
Preferred Note Plus
Two fixed-rate options. Choose the term that fits your timeline.
Preferred Note Plus is offered only to verified accredited investors under Rule 506(c) of Regulation D. Rates are fixed and annualized. Interest and principal are paid at maturity: May 31, 2027 for the 6 Mo Note and November 30, 2027 for the 12 Mo Note. $10,000 minimum. Open November 16 to 30, 2026 and limited to $10 million per Note; a Note may close sooner if its limit is reached. Notes are obligations of Groundfloor, are not bank deposits, are not FDIC-insured and involve risk of loss.
Get started
Set up your Groundfloor investor account.
Answer a few questions about your accreditation.
Submit an accepted document or verification letter.
Once approved, return to review and invest.
Choose the term that fits your goals. Open to accredited and non-accredited investors.
Accredited Investors
7.0%
Fixed Rate
Our shortest accredited term – a premium rate with a quicker return.
8.5%
Fixed Rate
A balanced structure – an elevated fixed rate over a one-year commitment.
Our highest fixed return – lock in a premium rate and earn monthly income for two years.
Fixed Rate
OPEN TO ALL INVESTORS

8.0%
Fixed Rate
6.0%
Fixed Rate
5.0%
Fixed Rate
5.0%
Fixed Rate
6.0%
Fixed Rate
3-Month Note
8.0%
Fixed Rate
12-Month Signature Note
Limited-Time Offer
Offer expires Monday, November 30th. Credited after your first Note funds. One per investor. See terms.
Bonus
Tier 1
Invest a minimum of $1,000 to claim this bonus.
*Paste code at checkout
Bonus
Tier 2
Real assets, real numbers
On $25,000 over 12 months, Groundfloor’s 8.0% Signature Note pays $2,000, while the 10.5% Preferred Note Plus pays accredited investors $2,625. Groundfloor Notes are not FDIC-insured and involve risk, including possible loss of principal.
If you invest
Over 12 months, Preferred Note Plus pays
Over 12 months, the Signature Note pays
$2,197 more$1,572 more
than the average 12-month bank CD on $25,000. The Signature Note pays $1,572 more.
Invest Now Not verified yet? See the four stepsThe dashed line is inflation: what $25,000 has to earn in a year just to keep its buying power ($850 at 3.4%). Bars that stop short of it are earning less than prices are rising.
Preferred Note Plus
6.1×
the average 12-month bank CD rate
10.5% fixed for accredited investors, through November 30.
Signature Note
4.7×
the average 12-month bank CD rate
8.0% fixed, open to every investor from $1,000.
Start small
$1,000
minimum for the 12 Mo Signature Note
Interest is paid every month.
Above inflation
2 of 5
options pay a rate above 3.4% inflation
Of the options in the chart above. Both are Groundfloor Notes.
Important information. Groundfloor Notes are not bank deposits, are not insured by the FDIC or any government agency, and involve risk, including possible loss of principal. Notes cannot be redeemed before maturity. Bank CDs, money market accounts and savings accounts are FDIC-insured up to applicable limits.
Earnings shown are simple interest for 12 months at the stated annualized rate, before taxes, and are for illustration only. They are not a guarantee of payment. Bank figures are national averages; individual banks may pay more or less. The inflation comparison is a simple difference between each rate and the 12-month change in consumer prices and is not a forecast.
Preferred Note Plus is offered only to verified accredited investors under Rule 506(c) of Regulation D, has a $10,000 minimum, pays interest and principal at maturity on November 30, 2027, and is open November 16 to 30, 2026, limited to $10 million. The 12 Mo Signature Note is offered under Regulation A; see the offering circular.
Sources: bank rates, FDIC National Rates and Rate Caps (12-month CD 1.71%, money market 0.58%, savings 0.39%). Inflation, U.S. Bureau of Labor Statistics, CPI-U all items, 12-month change of 3.4% for the 12 months ending . Groundfloor rates current as of .
1 Monthly active Notes investors as of , compared with the same month in 2025. Past performance does not guarantee future results.
Real Assets, Real Answers
You’re shopping around — good. Here’s how Groundfloor Notes stack up, and the questions worth asking anyone offering you a fixed return.
| Groundfloor Notes | Other Private Market Platforms | CDs / Savings | |
|---|---|---|---|
| Fixed yield | Up to 10.5%, locked at investment | Varies, often shown before fees | ~1.5% national average APY |
| Investor fees | None | Often 1–2%+ platform fees | None, capped rate |
| Backed by | First-lien residential real estate loans | Varies — not always disclosed | Cash deposit, no asset backing |
| Underwriting | Originated & underwritten by Groundfloor | Often a pass-through marketplace | N/A |
| Track record | 100% of Notes paid in full, on time, since 2018 | Varies | N/A |
Not all fixed income is built the same.
Before you commit anywhere — including here — ask these.
Are the terms really fixed?
Groundfloor locks your rate the moment you invest. Ask whether the other offer can change mid-term.
What’s actually backing this?
Every Groundfloor loan is secured by a first-lien position on real property. Ask what stands behind theirs.
Who’s underwriting the loans?
What’s the real track record?
Ask for actual repayment history, not projections. Ours is public — every Note paid in full since 2018.
What’s the exit if you need out?
SEE FOR YOURSELF
Term length, investor’s choice
LOCK IT IN
The rate you see is locked in for the entirety of the term you choose. No fees.
Pick Your Term
Groundfloor has originated $2.2 billion in real estate loans to vetted residential builders since 2013. Notes give you direct exposure to that loan engine without picking properties, managing tenants, or competing for deals
Your chosen rate and term are locked in the moment you invest, no matter what the market does.
Short-term loans go to residential builders for renovations, rehabs, and new construction.
In any recovery, Groundfloor's first-lien claim is paid before junior debt or equity.
Depending on the Note you choose, you may be paid interest either monthly or at maturity.
Depending on the Note you choose, you may be paid interest either monthly or at maturity.
Structural Details
Every Note is backed by a first-lien position on every property.
When a residential builder takes a loan from Groundfloor, the loan is secured by a first-lien position on the property. In any recovery scenario such as a sale, refinancing, or foreclosure — the first lien holder is paid before any other claim.
That's the same structure a bank uses when it issues a mortgage. The difference: with a Groundfloor Note, you're the one earning the yield on the loan instead of the bank.
First-lien protection doesn't eliminate risk. It defines where you sit in line if something goes wrong. The position itself is the structural advantage.
First-lien holder
(you, via Groundfloor) PAID FIRST
Second-lien / mezzanine debt
PAID AFTER
Junior Debt
PAID AFTER
Equity (the builder)
PAID LAST
Capital stack in a typical residential real estate loan
First-lien holder (you, via Groundfloor) PAID FIRST
Second-lien / Mezzanine Debt PAID AFTER
Junior Debt PAID AFTER
Equity (the builder) PAID LAST
Capital stack in a typical residential real estate loan
100% Repayment Track Record
Every Note Groundfloor has issued since the program launched in 2018 has paid 100% of principal and interest. The track record lives in our SEC filings.
Through inflation, rate hikes, and a regional banking crisis — every Note has paid in full and on time.
Funded across 12 years of operating history
Individual investors on the platform
Principal & interest paid on every Note since 2018
HOW NOTES COMPARE
Short-duration fixed income products differ in structure as much as in yield. Here is how the 12-month Signature Note sits next to the alternatives investors typically consider.
$15,000 INVESTED · 12 MONTHS
JUly 2026 RATES
JUly 2026 RATES
$15,000 in a Groundfloor 12-Month Signature Note earns $1,375 in interest + starting bonus over 12 months at 8.5% fixed rate.
You’ll receive $106.25 in interest each month, plus the $100 starting bonus.
The same $15,000 in a 12-month bank CD at the FDIC national average of 1.55% earns $232.50, paid once at maturity.
That’s $1,142.50 more in total earnings over the same 12-month period.
+$1,142.50
More interest than a CD over 12 months
Signature Note vs. 12-month bank CD on a $15,000 investment
New investors: invest $1,000+ in Notes and get a $100 bonus on top of your interest with NOTES100 — on a $15,000 Signature Note, that lifts first-year earnings to $1,375.00.

1.55% APY · FDIC national average · Paid at maturity
$100 minimum for 1mo/3mo, $1,000 for the 12mo Signature. Reg A qualified.
Illustrative comparison. Assumes $15,000 invested at 8.5% fixed APR in the Groundfloor 12-Month Signature Note (monthly distributions of $106.25 × 12 = $1,275.00 total interest) versus a 12-month bank CD at the June 2026 FDIC national average yield of 1.55%. Notes are not bank deposits and are not FDIC-insured. Past performance does not guarantee future results. $100 new-investor bonus available for a limited time on first investments of $1,000+ in Notes, subject to promotional terms. Bonus is not interest and not included in the chart figures.
The details
| ACCREDITED 12 MO PREFERRED NOTE PLUS |
EVERY INVESTOR GROUNDFLOOR SIGNATURE NOTE |
12-MONTH BANK CD (FDIC AVG) |
MONEY MARKET ACCOUNT (FDIC AVG) |
SAVINGS ACCOUNT (FDIC AVG) |
|
|---|---|---|---|---|---|
| Rate | 10.5% fixed | 8.0% fixed | 1.71% | 0.58% | 0.39% |
| Earns on $25,000 in 12 months | $2,625 | $2,000 | $428 | $145 | $98 |
| Rate compared with 3.4% inflation | 7.1 points above | 4.6 points above | 1.7 points below | 2.8 points below | 3.0 points below |
| Rate fixed for the term? | Yes, set at investment | Yes, set at investment | Yes | No, bank can change | No, bank can change |
| Interest paid | At maturity, Nov 30, 2027 | Monthly | Varies by bank | Monthly | Monthly |
| Minimum | $10,000 | $1,000 | Varies by bank | Varies by bank | Varies by bank |
| Access to your money | Held to maturity | Held to maturity | Early withdrawal penalty | Any time | Any time |
| FDIC insured? | No | No | Yes, to $250,000 | Yes, to $250,000 | Yes, to $250,000 |
| Can you lose money? | Yes | Yes | No, within FDIC limits | No, within FDIC limits | No, within FDIC limits |
| Who can invest | Verified accredited investors | Open to all | Anyone | Anyone | Anyone |
WHO NOTES ARE FOR
Notes are flexible, high-yield investments designed for any investor.
Notes give you a fixed alternative with monthly flexibility — high yields without giving up control of your cash for long lockups.
QUESTIONS
Notes are designed to be understood. If your question isn’t here, our Investor Success team is available at [email protected] — we don’t outsource to a chatbot.
A Note is a fixed-rate, fixed-term debt security — predictable income for a defined period.
We also offer an actively managed REIT with a 3-year vintage targeting a 9–10% IRR, individual LROs, and curated limited availability private market offerings for accredited investors. Many investors hold multiple.
LOCK IT IN
Skip the market swings and volatility.
Groundfloor Notes are offered under Regulation A of the Securities Act of 1933. Notes are not bank deposits, are not insured by the FDIC, and involve risk of loss. Past performance is not indicative of future results. All rates current as of May 2026 and may be adjusted monthly for new Notes. Read the offering circular before investing. © 2026 Groundfloor Finance Inc.”